Market overview and industry significance of the STEM Education In K-12 Market
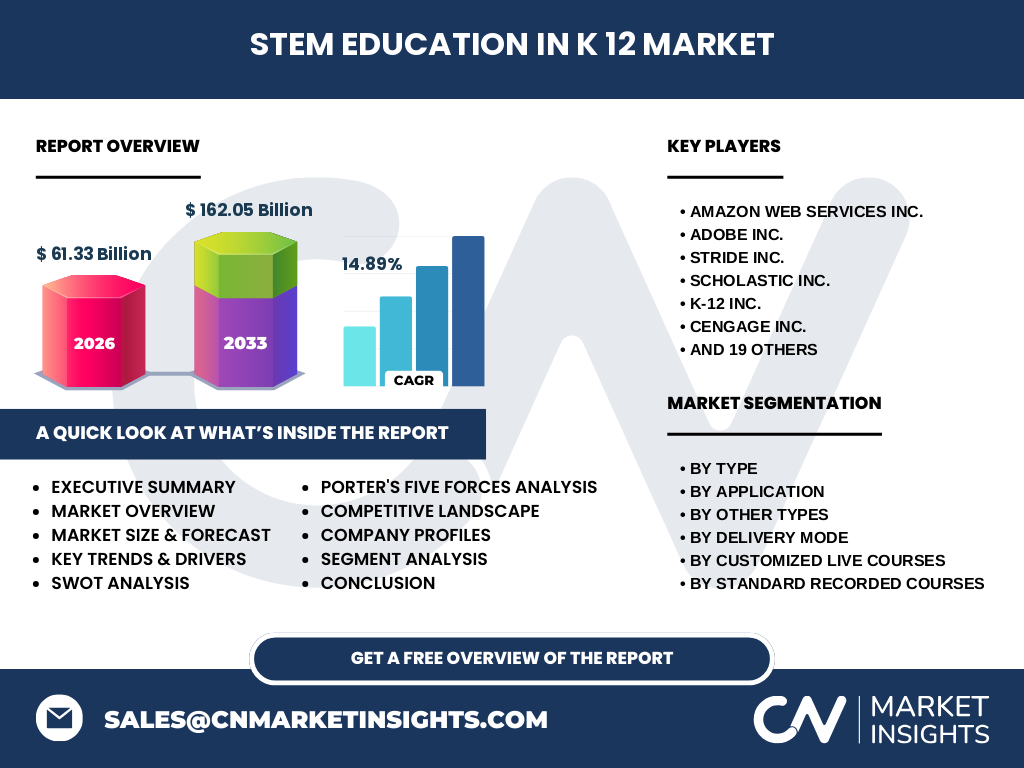
The STEM Education In K-12 Market serves as the foundational pillar for global digital literacy, reaching a valuation of 61.33 Billion in 2026. By integrating technical expertise with pedagogical frameworks, the industry bridges the skills gap in engineering, mathematics, and data science. Our research defines this scope as the intersection of hardware, like PASCO Scientific lab kits, and software-driven personalized learning platforms, essential for modern educational competitiveness.
Structural Growth Drivers and Market Constraints
Market expansion is fueled by policy-driven digital transformation and the increasing demand for high-skill labor. The STEM Education In K-12 Market faces logistical hurdles, notably infrastructure disparities in rural districts. However, innovation in gamified learning via Sphero Inc. and Wonder Workshop Inc. provides a significant opportunity to bypass legacy barriers, shifting from standard passive content to active, project-based engagement models that command higher market premiums.
Emerging trends and long-term growth patterns
A pivot toward hybrid stem education models and AR/VR integration is redefining engagement. zSpace represents this technical evolution, offering immersive experiences that physical textbooks cannot replicate. We anticipate a rapid adoption of Interactive STEM Learning Platforms, which move beyond static video toward real-time assessment, directly correlating with the projected shift toward high-value, tech-heavy instructional environments.
COVID-19 impact analysis and recovery trajectory
The pandemic acted as a catalyst for rapid digitization, forcing a sudden reliance on online delivery modes. While traditional offline models stagnated, firms like Outschool Inc. and D2L Corporation saw exponential user acquisition. This recovery trajectory solidified the necessity of blended learning architectures, ensuring that the current ecosystem is significantly more resilient and scalable than pre-2020 infrastructures.
Competitive landscape and strategic dynamics
The STEM Education In K-12 Market exhibits high concentration, with giants like McGraw-Hill Education and Houghton Mifflin Harcourt dominating via established textbook ecosystems, while Amazon Web Services Inc. provides the foundational cloud scaffolding. The strategic dynamic is co-opetition, where hardware providers like PASCO Scientific partner with software-heavy firms to create comprehensive, interoperable ecosystems that create high barriers to entry for smaller, niche EdTech startups.
Executive summary of the STEM Education In K-12 Market
Synthesizing our research, the STEM Education In K-12 Market is poised for explosive growth, scaling from 61.33 Billion in 2026 to a projected 162.05 Billion by 2033. This 14.89% CAGR is driven by the urgent need for future-ready technical competencies. Success in this vertical requires a sophisticated blend of curriculum efficacy, platform accessibility, and deep integration with existing school board procurement protocols.
Projected market growth from 2027 to 2033
Our modeling suggests that the industry will hit 162.05 Billion by 2033, reflecting a sustained 14.89% CAGR. This aggressive growth trajectory is supported by increased public-private partnerships and substantial reinvestment in specialized STEM facilities. The market is maturing, moving from general education software to highly specialized, high-ticket items like virtual labs and intensive STEM bootcamps.
Segmentation analysis by type and application
Segmentation reveals a bifurcation between Customized Live Courses and Standard Recorded Courses. The market role of Elementary School (K-5) applications is increasingly foundational, whereas High School (9-12) segments focus on career-ready technical certification. This split allows players like Cengage Inc. to target early-adopters, while Stride Inc. captures institutional long-term contracts for standardized virtual curriculum delivery.
Geographic distribution and performance analysis
Geographically, the STEM Education In K-12 Market is dominated by North American tech hubs, with rapid expansion in Asia-Pacific regions. Regional performance is dictated by regulatory bodies that standardize curriculum requirements. Emerging economies are favoring online delivery modes to bypass the logistical hurdles of physical infrastructure, while more established markets are emphasizing hybrid STEM education models that integrate legacy hardware with digital agility.
In-depth review of key regional markets
North America leads due to heavy investment by Adobe Inc. and local school district initiatives, while the Asia-Pacific segment is accelerating through aggressive government mandates. These regions utilize distinct logistical hurdles to favor specific models; for instance, the vast geography of North America promotes Virtual STEM Labs, whereas denser regions favor intensive, localized in-person bootcamps to foster collaborative learning environments.
Strategic positioning of leading companies
Top-tier companies like K-12 Inc. and School Specialty have secured market share by owning the supply chain from content to equipment. Conversely, innovators like Innova STEM Education focus on agile pedagogy, while Mathspace Pty Ltd. leverages AI for adaptive learning. This competitive positioning indicates a market where specialized intellectual property is just as valuable as physical distribution networks in maintaining long-term institutional loyalty.
Porter's Five Forces assessment
Threats of new entrants are mitigated by high procurement barriers, while the bargaining power of buyers remains strong due to centralized school district budget cycles. Competitive rivalry is intense, focused on digital platform superiority. We note that supplier power is low, given the commoditization of raw instructional hardware, forcing companies to pivot toward value-added, subscription-based services to maintain profitability.
SWOT analysis of the industry participants
Strengths: Established institutional relationships and pedagogical depth. Weaknesses: High customer acquisition costs and slow procurement cycles. Opportunities: Global expansion in emerging markets and the rise of VR/AR tech. Threats: Changing regulatory mandates and the potential for content piracy in digital marketplaces. Firms that capitalize on project-based learning and interactive platforms appear best positioned to neutralize these threats.
Value chain analysis for industry structure
The value chain originates with content developers and raw hardware manufacturers like PASCO Scientific, flowing through digital distribution platforms, and concluding with end-users in K-12 institutions. Value is increasingly concentrated in the Platform-as-a-Service (PaaS) layer. Success depends on the ability to integrate hardware into the software flow, reducing friction for educators while providing actionable data to school administrators.
Investment insights and high-potential areas
Strategic investment should prioritize interactive STEM learning platforms and hybrid, project-based models. Given the 14.89% CAGR, the most potential lies in companies that bridge the gap between virtual reality (VR) experiences and real-world curricula. We recommend focusing on firms that offer personalized stem education programs, as these address the critical need for differentiated instruction in large, heterogeneous classroom settings.
Conclusion and key takeaways
The STEM Education In K-12 Market represents a robust, 162.05 Billion opportunity by 2033. The convergence of gamified engagement and standardized, measurable learning outcomes is the primary engine of success. For stakeholders, the imperative is clear: transition from transactional hardware sales to long-term, subscription-based instructional ecosystems that provide measurable, high-impact results for both students and institutional decision-makers.
Research methodology for triangulation
Our methodology employs a rigorous triangulation approach. We aggregate data from international trade registries, proprietary interviews with C-suite executives at D2L corporation and Cengage Inc., and secondary macroeconomic indicators. Baseline estimates are stress-tested against regional policy shifts to ensure accuracy in our 2027-2033 forecast, ensuring all findings meet professional standards for investment-grade market intelligence.
Scope of the report and coverage parameters
This analysis covers the global STEM Education In K-12 Market, encompassing hardware, software, and instructional services. Limitations include variations in national school funding cycles and regional regulatory constraints. The report parameters strictly focus on K-12, excluding higher education or corporate training, to ensure deep, actionable insights into the Elementary, Middle, and High School segments specifically.
Recent developments, partnerships, and strategic moves
Recent industry shifts include significant M&A activity where traditional publishers acquire digital-native EdTech startups to modernize their portfolios. Notable partnerships between Hurix Systems Pvt. Ltd. and regional school systems demonstrate the trend toward localized curriculum adaptation. These developments indicate an industry in the middle of a massive digital pivot, characterized by rapid product launches in AR/VR content and subscription-based, self-paced tutorials.